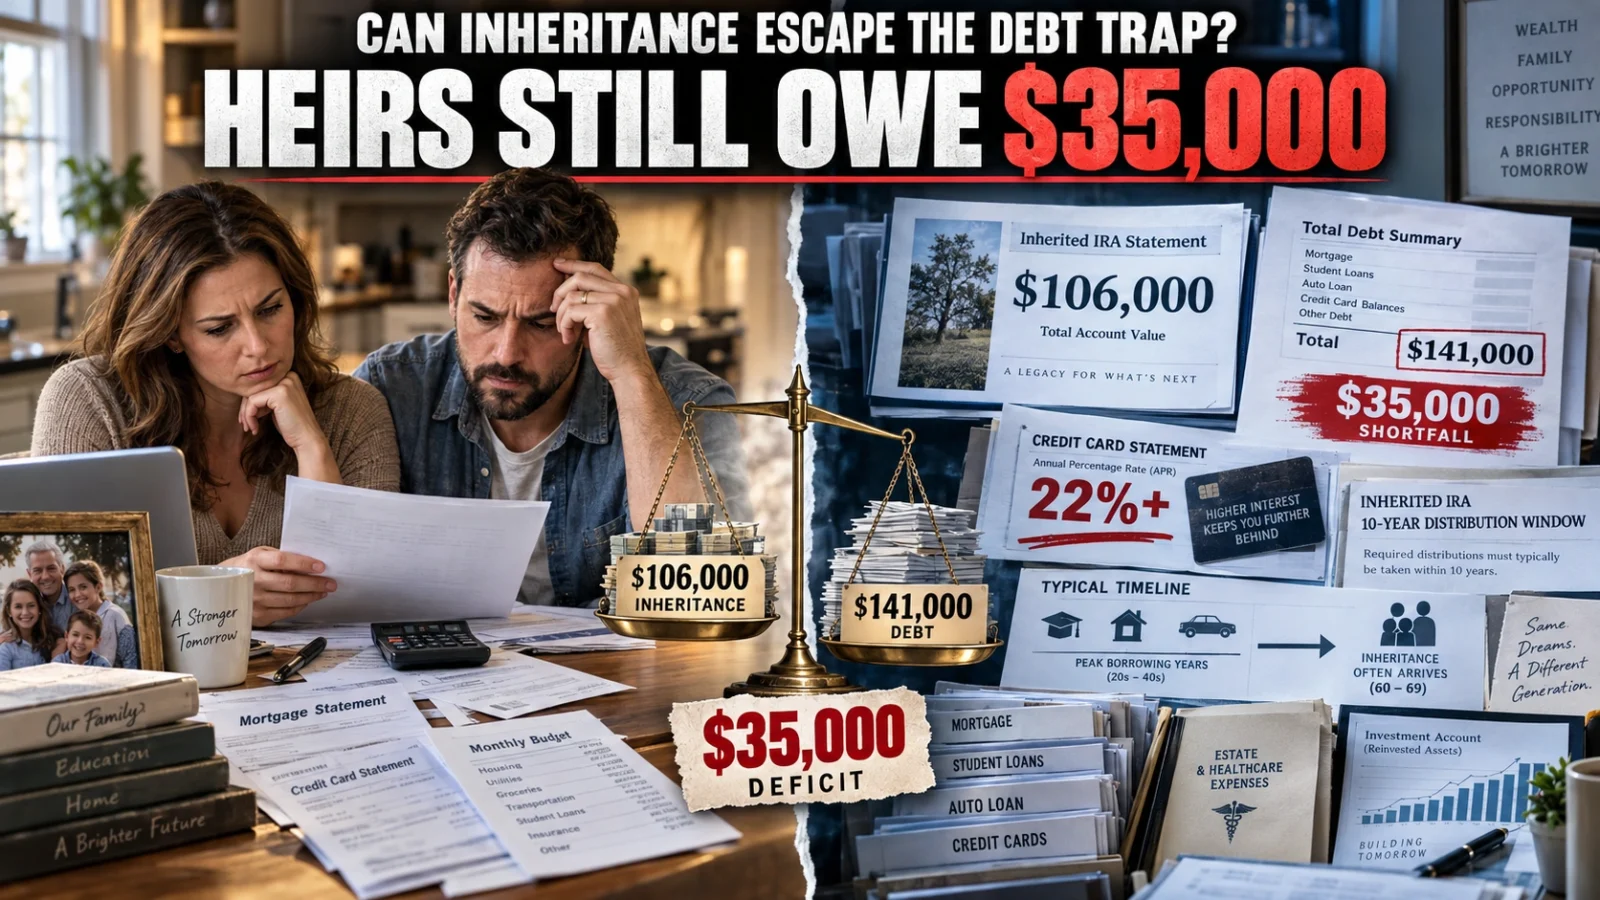
A comprehensive study of nearly 58,000 retirement account beneficiaries conducted by Vanguard reveals that the promised salvation of the “Great Wealth Transfer” is colliding with an unforgiving economic reality1. The typical heir inherits an individual retirement account balance that falls $35,000 short of what they already owe in outstanding liabilities1.
Rather than wiping household balance sheets clean, the long-anticipated intergenerational wealth handover is landing inside families already burdened by elevated borrowing costs, mortgages, and persistent living expenses1. With average credit card interest rates exceeding 22% and everyday expenses straining domestic budgets, the gap between inheritance expectations and actual debt threatens to dissolve family legacies before they can take root2.
This shortfall directly hits millions of mid-career American workers and families who have deferred vital financial stability while anticipating generational relief1. Instead of gaining financial independence, ordinary households are discovering that modern debt structures are engineered to absorb incoming assets long before family wealth can compound2.
The Two-Decade Timing Gap: When Need and Capital Collide
The core driver of the inheritance crisis is a profound chronological mismatch between when Americans need liquidity and when they actually receive it1. Vanguard’s research shows that 97% of heirs receive an inheritance only after the grantor passes away, meaning bequests overwhelmingly arrive when beneficiaries are in their early sixties2. The frequency of inheritance receipt peaks between ages 60 and 69, a life stage when workers are winding down their careers and approaching retirement themselves2.
Conversely, peak borrowing and domestic financial pressure arrive two decades earlier during a worker’s thirties and forties1. Households in their forties carry an average debt-to-income ratio of 29%, nearly triple the 9% ratio reported by adults in their twenties1. Because bequests arrive twenty years after families shoulder major mortgage obligations, childcare expenses, and education costs, capital arrives far too late to alleviate peak borrowing stress1.
Inside the $141,000 Deficit: How Modern Borrowing Outweighs Inheritances
Across the broader pool of beneficiaries who inherited an IRA, 54% carried outstanding debt balances2. Among these indebted heirs, the average cumulative liability reached $141,000, dwarfing the average inherited IRA balance of $106,0001. The resulting $35,000 net deficit means the majority of indebted heirs remain in negative territory even after liquidating the entire transfer1.
These liabilities encompass an aggressive blend of residential mortgages, student loans, auto financing, and high-interest credit card debt1. Credit card balances are particularly corrosive, as roughly 7% of balances transitioned into delinquency over the past year across the United States1. For working parents juggling monthly loan payments, a five-figure inheritance cannot outpace decades of accumulated compound interest1.
Generational Disparities: How the Debt Gap Distorts Net Worth
The financial impact of an inheritance changes dramatically depending on the age at which a beneficiary receives it1. While younger workers experience transformative balance sheet improvements from an inheritance, the vast majority of distributions are concentrated among older cohorts who have already navigated their primary earning and borrowing years1.
| Age Cohort of Heir | Average Debt-to-Income Ratio | Surge in Investable Assets | Surge in Reported Net Worth | Frequency of Inheritance Arrival |
|---|---|---|---|---|
| Ages 20–29 | ~9%1 | Baseline entry1 | Baseline entry1 | Extremely rare2 |
| Ages 30–39 | ~20%–25% (Escalating)2 | ~66% boost1 | ~80% boost2 | Low / Early career2 |
| Ages 40–49 | ~29% (Peak leverage)1 | ~45%–50% boost2 | ~55% boost2 | Moderate2 |
| Ages 60–69 | ~18% (De-leveraging)2 | ~22% boost1 | ~25%–30% boost2 | Peak concentration (~4% annually)2 |
| Ages 70–79 | ~11% (Late baseline)2 | ~16% boost1 | ~21% boost2 | Low / Diminishing2 |
The figures illustrate that receiving an inheritance in one’s thirties expands investable assets by 66% and increases net worth by 80%1. For recipients in their sixties, the identical financial transfer produces only a 22% increase in investable assets1. Systemic capital flow delays deprive younger families of wealth acceleration when it would yield the highest lifetime benefit1.
The Mental Accounting Trap: Reinvesting While Interest Compounds
Beyond mechanical deficits, behavioral habits prevent heirs from utilizing windfalls effectively1. Vanguard discovered that 68% of heirs reinvest their inheritance into capital markets, while a mere 11% allocate any portion toward retiring existing debt1. Heirs consistently segregate incoming assets from personal liabilities, treating the inheritance as isolated wealth rather than addressing their overall balance sheet1.
This behavioral split results in severe value destruction for working families2. An heir who reinvests an inherited IRA into index funds yielding 7% to 9% while carrying revolving credit card debt at 22% interest guarantees an ongoing net loss2. As Vanguard investment strategy analyst and behavioral scientist Malena de la Fuente noted, inheritance represents a primary opportunity to eliminate high-interest liabilities and secure guaranteed financial returns1.
Many heirs avoid using inherited money to pay down debt because they view family bequests as sacred capital that must remain preserved1. Treating inheritances as untouchable investments allows consumer creditors to continue extracting interest from the family’s monthly income2. Breaking this psychological barrier is critical to preventing generational wealth from eroding under modern credit terms1.
The Tax and Healthcare Siphon: Shrinking Estates Before Probate
Federal regulatory shifts have significantly complicated the administration of inherited retirement accounts4. Under changes codified by the federal SECURE Act, non-spouse beneficiaries can no longer stretch inherited IRA distributions across their lifetimes4. Beneficiaries must now fully liquidate the account within a strict 10-year window, often pushing mid-career heirs into higher federal and state income tax brackets2.
Concurrently, rising eldercare costs and out-of-pocket medical expenditures rapidly deplete parental savings before estates ever reach heirs2. Nursing home facilities, assisted living, and prolonged memory care routinely consume parental home equity and taxable reserves2. By the time probate concludes, estates that heirs assumed would cover their family mortgages have frequently been dismantled by long-term care providers2.
The confluence of forced tax distributions and medical attrition transforms what should be a financial windfall into an administrative burden2. Middle-class households often find that the after-tax, post-probate remainder fails to cover basic debts accrued during their prime working years1. Without early planning, the modern healthcare and tax systems capture the wealth that prior generations spent lifetimes accumulating2.
The Silence Barrier: Why Half of American Families Never Discuss Wealth
Compounding the financial shortfall is an entrenched culture of silence around domestic finances2. Vanguard’s analysis revealed that only 54% of heirs ever had a concrete conversation with their benefactors regarding their inheritance prior to receiving it2. Familial avoidance was largely driven by cultural taboos surrounding personal finances or assumptions that the grantor would feel uncomfortable discussing mortality2.
This communicative failure blocks strategies such as lifetime giving, which transfers assets when adult children need them most2. By withholding assets until death, parents miss the window to help children eliminate student loans, fund down payments, or avoid credit card debt1. Transparent communication allows families to coordinate estate strategies before compounding debt degrades the next generation’s standard of living2.
Proactive planning significantly alters how beneficiaries process financial transfers2. While 50% of heirs report overall peace of mind after receiving an inheritance, engaging in advance discussions with benefactors increases that peace of mind by 9 percentage points2. Consulting a professional financial advisor produces an even larger increase of 23 percentage points, standing as the single most effective action in stabilizing the recipient’s outlook2.
What Happens Next
Over the next two decades, an estimated $100 trillion will move between generations, yet without behavioral adjustments, the majority of that capital will be consumed by debt and taxes2. Financial institutions are increasingly urging families to consider lifetime giving strategies rather than waiting for posthumous probate transfers2. Transferring smaller gifts during peak borrowing years can shield adult children from high interest rates and provide far greater long-term economic leverage1.
For heirs, closing the $35,000 debt gap requires confronting the psychology of mental accounting directly1. Financial planners advise recipients to prioritize liquidating high-interest consumer liabilities before deploying funds into speculative investment products2. Unless American households align family transfers with peak borrowing windows, the Great Wealth Transfer will function primarily as a balance sheet transfer to commercial lenders rather than a foundation for future security1.
Vanguard – https://corporate.vanguard.com/content/corporatesite/us/en/corp/articles/how-inheritance-changes-lives.html
TheStreet – https://www.thestreet.com/personal-finance/vanguard-inheritance-ira-heirs-owe-35000-more-debt-timing-gap
TheStreet (Personal Finance) – https://www.thestreet.com/personal-finance/vanguard-says-30-of-millionaires-feel-broke-but-it-can-be-fixed
TheStreet (Financial Habits) – https://www.thestreet.com/personal-finance/vanguard-on-five-habits-that-predict-your-financial-future
Facebook (The Island Packet Post) – https://www.facebook.com/islandpacket/posts/the-typical-inherited-retirement-account-falls-35000-short-of-what-the-heir-owes/1747030524096786/
Facebook (Belleville News-Democrat Post) – https://www.facebook.com/BellevilleND/photos/the-typical-inherited-retirement-account-falls-35000-short-of-what-the-heir-owes/1680503964083126/
Works cited
Vanguard flags a sobering debt gap facing most heirs – TheStreet,
How inheritance changes lives | Vanguard,
Vanguard says 30% of millionaires feel broke, but it can be fixed,
The typical inherited retirement account falls $35,000 short of what,

Leave a Reply