Oct 1, 2026
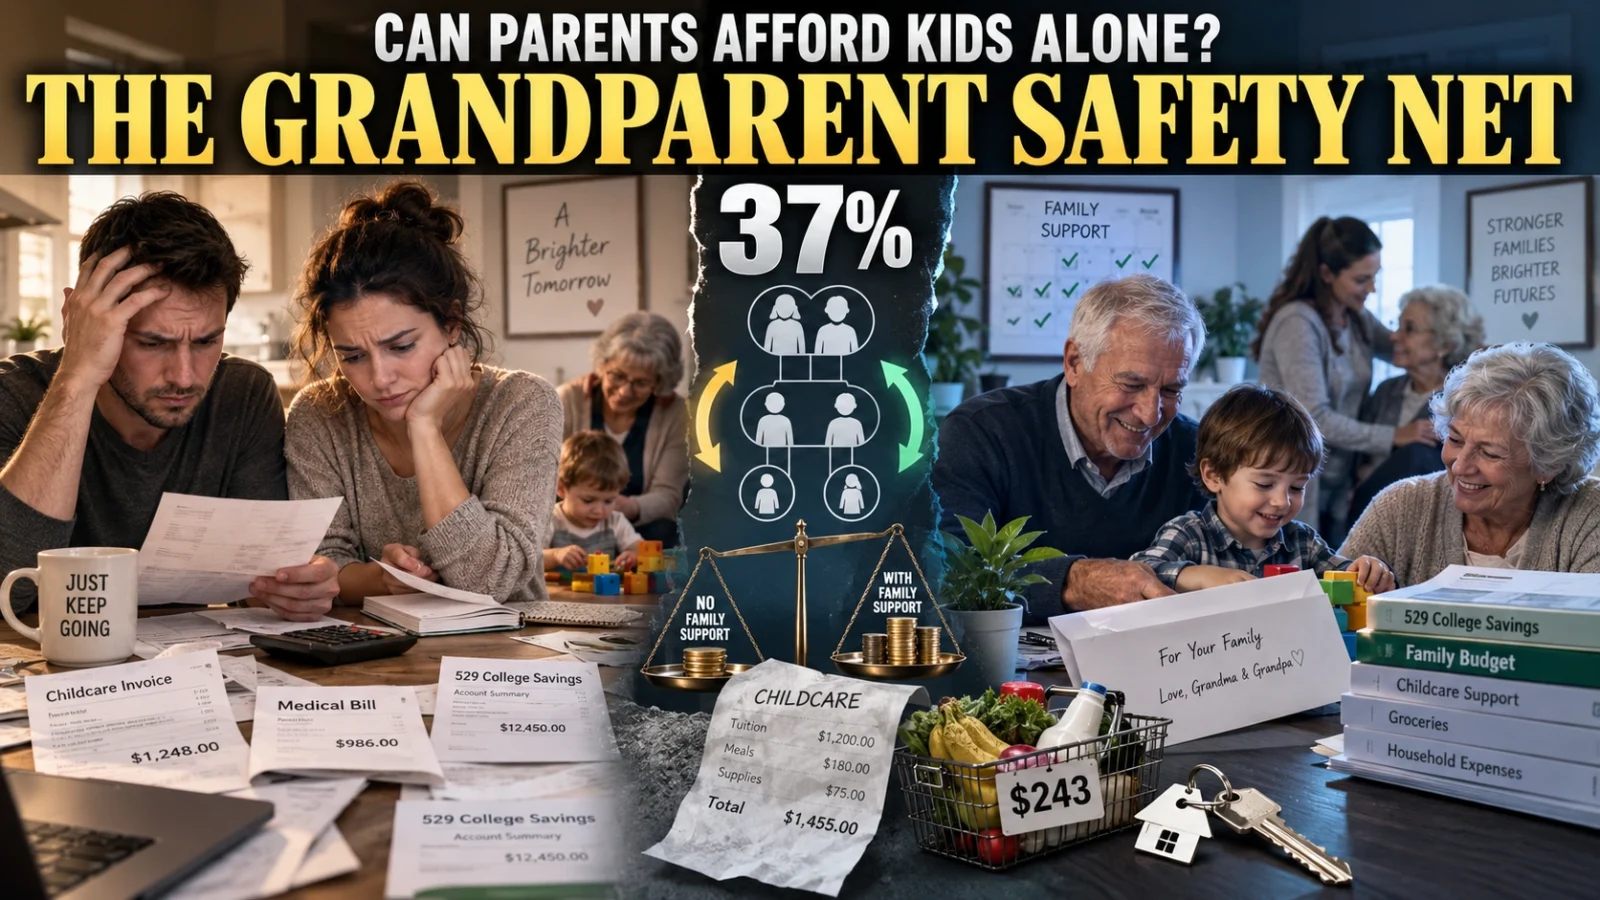
Nearly two in five American parents of young children, 37%, expect to get financial help from their own parents or grandparents in the coming year, or plan to ask for it. The figure comes from the BMO Real Financial Progress Index, a survey of 2,500 U.S. adults conducted by Ipsos from June 8 to July 13, 2026, and released by BMO on August 20. Fortune brought the finding wider attention on September 27.
The same survey found that 82% of parents say the cost of raising children has “gotten out of control,” and 76% say help from extended family is now essential to afford opportunities for their kids. Cash for everyday bills, free babysitting from grandparents and contributions to college savings are filling gaps that a single household’s earnings no longer cover.
This matters because family money is not evenly shared. Parents whose own parents have savings, live nearby and are healthy enough to help get a cushion. Parents without that safety net face the same bills alone, and that difference can follow their children into adulthood.
What the survey found
Among parents who expect family help, 47% said it would come as cash for day-to-day expenses, according to BMO. Another 43% said grandparents would provide free childcare or cover its cost, and about 26% said relatives would fund their children’s 529 college plans or other savings.
Parents also listed what their money goes to each year. On average, they estimated spending $5,498 on groceries, $2,469 on childcare, $2,445 on healthcare and $1,886 on college savings. Eighty-six percent said everyday costs such as daycare, camps and school supplies hurt their ability to save for their children’s future.
Readers should weigh the numbers with care. This is a bank’s own consumer survey, drawn from an online Ipsos panel and weighted to census figures, with a reported credibility interval of plus or minus 2.4 percentage points for the full sample. BMO did not publish how many of the 2,500 respondents were parents of young children, so the margin for that subgroup is likely wider. The survey measures what parents expect and believe, not audited household finances.
Not a paycheck collapse, but a squeeze
The popular story that middle-class wages have collapsed does not match the data. The Census Bureau reported in September that median household income reached $87,460 in 2025, the highest on record, and Pew Research Center found that middle-income households’ median income rose about 60% from 1970 to 2022 after inflation.
The squeeze comes from two other directions. First, the middle class has fallen behind those at the top: Pew found upper-income households’ median income grew 78% over the same period, and the middle class’s share of all household income dropped from 62% to 43%. Second, the specific costs of raising a family, especially childcare and food, have climbed sharply.
| Measure | Figure | Source |
|---|---|---|
| Median household income, 2025 | $87,460 (record high) | Census Bureau |
| Middle-income median income growth, 1970–2022 | +60% | Pew Research Center |
| Upper-income median income growth, 1970–2022 | +78% | Pew Research Center |
| Middle class’s share of all household income | 62% (1970) to 43% (2022) | Pew Research Center |
| Childcare share of income, average parent | 20% | Care.com 2026 Cost of Care |
| Federal affordability benchmark for childcare | 7% of family income | HHS, via Care.com |
| Grocery prices since 2019 | +33% | BLS, cited by BMO |
Childcare shows the gap most starkly. Care.com’s 2026 report found the average parent spends about 20% of household income on care, nearly three times the federal benchmark, and about one in five parents spends more than $30,000 a year, Fortune reported. When a single cost eats a fifth of income, even record-high earnings can feel inadequate.
Grandparents as unpaid infrastructure
For families who have them nearby, grandparents now function like a private social program. BMO found that 45% of Americans with young children live close to family who can help. Those parents reported saving about $1,915 a year on childcare, spending $1,646 instead of $3,561, and $1,443 a year on groceries.
The help reaches into the biggest purchase most families make. According to Fortune’s reporting on BMO’s research, 60% of Gen Z homeowners and 57% of millennial homeowners said they could not have bought their home without family support.
What BMO describes as a family choice is also, in our view, a sign of gaps in public support. Where affordable childcare and housing are scarce, a grandmother’s free afternoons and a grandfather’s savings account become the difference between a parent keeping a job and leaving it. Families with no such help absorb the full cost.
A two-way street with a heavy toll
Family help rarely flows in one direction. BMO found that 70% of parents with local family support are also responsible for the financial or emotional well-being of their own aging parents, compared with 45% of parents without family nearby. About seven in ten parents living near relatives identified as part of the “sandwich generation,” caring for children and older relatives at once.
That obligation carries real costs. Sixty percent of parents who get childcare help from local family said they treat giving money to extended family as a fixed monthly expense, like rent or a utility bill. Across all sandwich-generation parents, caregivers estimated spending $2,865 a year on relatives.
The help does not erase stress, either. Parents living near family who provide childcare were more likely to say they regularly feel overwhelmed by financial responsibilities, 74% versus 57%, according to BMO. “Family caregiving is often a reciprocal arrangement—and it can be a lot when you’re already stretched thin,” said Robin Growley, BMO’s U.S. head of consumer products.
Who gets left out
The much-discussed “Great Wealth Transfer” is large but lopsided. Cerulli Associates projects $124 trillion will change hands through 2048, with $105 trillion going to heirs. But more than half of the total, about $62 trillion, is expected to come from high-net-worth and ultra-high-net-worth households that make up only 2% of all households, according to Cerulli’s figures as reported by the National Association of Plan Advisors.
Wealth today is similarly concentrated. Fortune, citing Federal Reserve data, reported that the top 1% of households held roughly 30% of total assets in the second quarter of 2026, compared with about 5% for the bottom half.
Race sharpens the divide. The Federal Reserve’s 2022 Survey of Consumer Finances found the gap between the median white family’s wealth and that of the median Black or Hispanic family exceeded $220,000. A 2023 Boston Fed working paper found that about a third of white families aged 55 and older had ever received an inheritance, compared with 14% of Black families and 8% of Hispanic families.
In our analysis, when family money becomes a routine part of affording children, homes and college, advantage passes down through families as much as it is earned. Parents with no family wealth to draw on are not failing; they are competing against households that receive a subsidy they cannot access.
What parents fear next
Parents’ worries extend past this year’s bills. BMO found that 77% of parents actively worry about their children’s financial future, and 78% worry about how the rapid rise of artificial intelligence will affect their children’s ability to earn a living.
The same parents are not uniformly pessimistic. Forty-two percent said AI will ultimately better prepare the next generation for financial success, and 23% already use AI tools to manage family finances, including 30% of millennial parents. Fifty-four percent of parents with children at home said they feel they are making real financial progress.
Two incomes are no guarantee of calm. BMO found that 72% of dual-income households experience regular financial stress. For families already leaning on grandparents, the open question is what replaces that support when grandparents age, need care themselves, or are gone.
What happens next
BMO publishes its Real Financial Progress Index quarterly, so later editions will show whether reliance on family help is rising or easing. A year ago, BMO reported that 45% of households with children under 18 expected to depend on parents or grandparents, though differences in question wording mean the two figures may not be directly comparable.
The Federal Reserve’s triennial Survey of Consumer Finances, last published with 2022 data in October 2023, is the most authoritative source on how often families receive gifts and inheritances. Its next edition, covering 2025, will offer a firmer test of whether family transfers are becoming more common and more unequal.
For families, BMO recommends talking openly across generations about money and meeting with a financial adviser together. That conversation should include the day grandparents may need support themselves. For policymakers, the survey is a reminder that childcare, housing and eldercare costs are being absorbed by families who can afford to absorb them, and pushed onto families who cannot.
Sources
BMO, “BMO Real Financial Progress Index: 82% of American Parents Say Costs are ‘Out of Control'” (August 20, 2026): https://usnewsroom.bmo.com/2026-08-20-BMO-Real-Financial-Progress-Index-82-of-American-Parents-Say-Costs-are-Out-of-Control
Fortune, “In the affordability crisis, 37% of parents are counting on financial help from the Bank of Baby Boomers” (September 27, 2026): https://fortune.com/2026/09/27/affordability-crisis-37-parents-financial-help-baby-boomers/
Care.com, “This is how much child care costs in 2026” (2026 Cost of Care Report): https://www.care.com/c/how-much-does-child-care-cost
FOX 29, report on Census Bureau 2025 household income data (September 17, 2026): https://fox29.com/news/americans-household-income-higher-data
Newsweek, on Pew Research Center’s analysis of the American middle class: https://www.newsweek.com/1913772
Pew Research Center, “5 takeaways about the American middle class” (2015): https://www.pewresearch.org/short-reads/2015/12/10/5-takeaways-about-the-american-middle-class/markdown
Cerulli Associates, “Cerulli Anticipates $124 Trillion in Wealth Will Transfer Through 2048”: https://www.cerulli.com/press-releases/cerulli-anticipates-124-trillion-in-wealth-will-transfer-through-2048
National Association of Plan Advisors, “Wealth Transfers Expected to Hit $124 Trillion Through 2048”: https://www.napa-net.org/news/2024/12/wealth-transfers-expected-to-hit-$124-trillion-through-2048/
Federal Reserve, “Greater Wealth, Greater Uncertainty: Changes in Racial Inequality in the Survey of Consumer Finances” (October 18, 2023): https://federalreserve.gov/econres/notes/feds-notes/greater-wealth-greater-uncertainty-changes-in-racial-inequality-in-the-survey-of-consumer-finances-20231018.html
Federal Reserve Bank of Boston, working paper on inheritances and racial wealth gaps (2023): https://www.bostonfed.org/-/media/Documents/Workingpapers/PDF/2023/cpp20230307.pdf
PlanAdviser, “US Families Juggle Financial Support Across Generations” (2025): https://www.planadviser.com/us-families-juggle-financial-support-across-generations/
Fast Company, “Raising kids has gotten so expensive, parents are turning to an unexpected lifeline”: https://www.fastcompany.com/91608357/raising-kids-has-gotten-so-expensive-parents-are-turning-to-an-unexpected-lifeline

Leave a Reply