A 7% mortgage rate is not historically extraordinary. The United States lived with rates near that level around the turn of the century, and mortgage costs climbed far higher during the early 1980s.
What has changed is everything attached to that 7%.
The latest Freddie Mac reading available before publication put the average 30-year fixed mortgage at 7.03% on September 24, 2026, up from 6.30% a year earlier. Then, on September 30, the Mortgage Bankers Association reported that the average contract rate on conforming 30-year mortgages had reached 7.30% for applications filed during the week ending September 25. The two surveys use different methodologies, but both show borrowing costs climbing sharply again.
For would-be homeowners, the problem is no longer simply the interest rate. It is the combination of a roughly 7% mortgage with home prices that have risen dramatically faster than they did in previous generations, much larger down payments, expensive property insurance and taxes, and incomes that have not kept pace with the cost of entering the housing market.
That combination turns what once looked like an ordinary mortgage rate into something that can consume a family’s budget before groceries, child care, health insurance, transportation or retirement savings enter the equation.
The same 7% rate now sits on a mortgage nearly three times as large
The simplest way to understand today’s affordability crisis is to compare two moments when mortgage rates were almost identical.
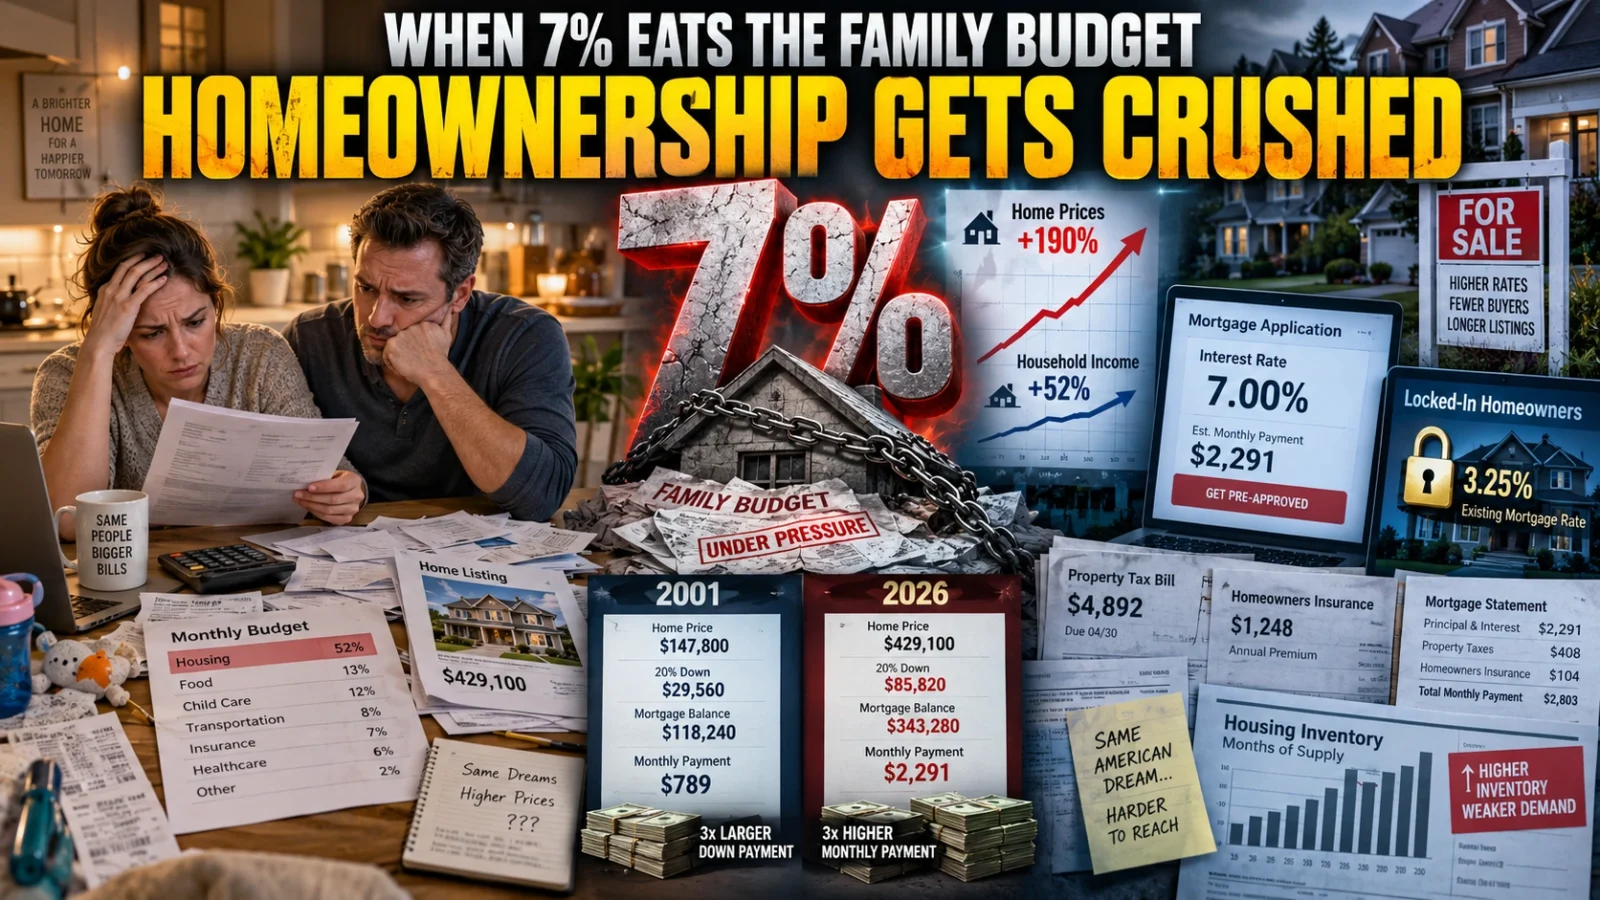
In 2001, the average 30-year mortgage rate was about 7.03%, according to historical housing data compiled using Freddie Mac and National Association of Realtors figures. The median existing-home price that year was about $147,800. U.S. median household income was $42,228.
In August 2026, the median existing-home price was $429,100. The latest Census Bureau annual income data put median household income at $87,460 in 2025.
Using a 20% down payment and a 30-year loan, the difference is stark:
| Comparison | 2001 | 2026 benchmark |
|---|---|---|
| Mortgage rate | 7.03% | 7.03% |
| Median existing-home price | $147,800 | $429,100 |
| 20% down payment | $29,560 | $85,820 |
| Mortgage amount | $118,240 | $343,280 |
| Approx. monthly principal and interest | $789 | $2,291 |
| Median household income | $42,228 | $87,460 |
| Principal-and-interest payment as share of monthly median income | about 22% | about 31% |
The calculation is illustrative and excludes property taxes, homeowners insurance, mortgage insurance, homeowners-association fees, utilities and maintenance. The 2026 comparison also combines the latest available August home price with 2025 annual household income because full-year 2026 income data do not yet exist.
But that limitation makes the broader point stronger, not weaker: the basic mortgage alone now demands a substantially larger share of a typical household’s income at almost exactly the same interest rate.
The monthly principal-and-interest payment in this comparison is nearly three times as large as it was in 2001, while median household income has only a little more than doubled.
Home prices broke the old relationship with income
America’s housing problem was building before mortgage rates returned to 7%.
The Harvard Joint Center for Housing Studies reported in June that existing-home prices remained roughly 54% higher than in 2020 and were close to five times median household incomes nationally. In the 1990s, the price-to-income ratio was closer to three.
That matters because interest rates operate on the amount borrowed.
A 7% rate on a $120,000 mortgage and a 7% rate on a $340,000 mortgage may carry the same percentage label, but they do not create anything close to the same household expense.
Harvard estimated that the total monthly cost of purchasing a median-priced home — including principal, interest, property taxes, insurance and mortgage insurance under its assumptions — rose from roughly $1,700 in early 2020 to $3,100 by the fourth quarter of 2025. It estimated that a household needed more than $120,000 in annual income to afford that payment, compared with about $66,000 in 2020.
Meanwhile, home prices have not undergone the broad collapse that high borrowing costs might once have produced.
The Federal Housing Finance Agency reported on September 29 that nationwide house prices were still 2.6% higher in July 2026 than a year earlier. The S&P Cotality Case-Shiller national index similarly showed a 1.9% annual increase in July.
Prices are cooling in inflation-adjusted terms and some cities are experiencing declines. But nationally, the hoped-for bargain — much lower home prices offsetting much higher interest rates — has largely failed to materialize.
The down payment has become its own barrier
Monthly payments receive most of the attention, but buyers must first survive another test: accumulating enough cash to purchase the home.
Twenty percent of the 2001 median existing-home price was about $29,560.
Twenty percent of today’s $429,100 median is $85,820.
That does not mean buyers must always put 20% down. FHA, VA and conventional programs can allow much smaller down payments, depending on eligibility and loan structure.
But lower down payments generally mean larger mortgages, and they can add mortgage-insurance costs.
For households already paying rent, car loans, child-care bills and student debt, accumulating even 3% or 5% of a $400,000 home can require years of savings.
The consequences are visible in who is actually reaching homeownership.
The National Association of Realtors reported that first-time buyers represented just 21% of recent purchasers in its 2025 survey, the lowest share in records dating to 1981. The median first-time buyer was 40 years old, compared with buyers in their late 20s during the 1980s.
The report linked those delays to a combination of high housing costs, limited inventory, rent burdens and debts including student loans, credit cards and car payments. Those findings describe successful recent buyers and should not be interpreted as a census of every American trying to purchase a home.
Still, the generational shift is difficult to ignore.
For many households, homeownership is no longer delayed by a few years.
It is delayed into middle age.
A 7% mortgage is only the first housing bill
Comparing principal and interest alone also understates today’s pressure.
Homeowners must pay property taxes. They generally need homeowners insurance. They face repairs, utilities, roofs, plumbing, heating systems and other expenses renters may not pay directly.
Insurance has become an especially significant additional burden in many parts of the country.
The Bureau of Labor Statistics’ producer-price measure for homeowners insurance rose from an index level of roughly 211 in early 2020 to about 290 by August 2026 — an increase of more than one-third. The measure tracks prices received by insurers and is not identical to an individual household’s premium, which varies dramatically by state, risk and property.
That distinction matters because a buyer may qualify for a mortgage based on one estimate of taxes and insurance, only to face higher escrow payments later.
Climate risk has intensified that problem in some regions as insurers reprice wildfire, hurricane, flood and severe-weather exposure. In other places, rising construction and repair costs have increased the cost of claims.
A mortgage payment that consumes 30% of gross income can therefore become a much larger housing burden once everything required to keep the home is included.
The result is a form of financial compression: housing absorbs the money that would otherwise flow toward food, emergency savings, medical care, children’s expenses or retirement.
The homeowner owns an appreciating asset.
But the household may have very little cash left to live.
Low-rate homeowners are trapped while new buyers face the full market price
High mortgage rates are also creating two different housing economies.
Millions of existing homeowners refinanced or purchased during the ultra-low-rate period of 2020 and 2021.
The Federal Reserve reported this year that a majority of outstanding mortgages still carry interest rates below 4%. Economists describe the resulting behavior as the mortgage “lock-in” effect: homeowners hesitate to move because selling could mean surrendering a 3% mortgage and replacing it with one near 7%.
Consider the financial penalty.
On a $343,280 mortgage, a 3% 30-year rate produces a principal-and-interest payment of roughly $1,447 a month.
At 7.03%, the same loan is about $2,291.
That is roughly $844 more every month before taxes and insurance — more than $10,000 a year.
For an existing homeowner, that difference can make a job relocation, divorce, marriage, larger home, smaller home or move closer to family financially unattractive.
For a first-time buyer, there is no old mortgage to protect.
They enter directly at today’s price and today’s rate.
This creates an unusual housing imbalance. Existing owners may sit on substantial equity and exceptionally cheap debt, while younger or lower-wealth households face both elevated prices and expensive financing.
The same market therefore rewards the household that already owns housing while raising the entry cost for the household trying to acquire its first home.
Buyers are pulling back — but sellers have not cut prices enough
The pressure is now visible in transaction data.
On September 30, the Mortgage Bankers Association said total mortgage applications fell 6% in one week as its conforming 30-year mortgage rate rose to 7.30%. Purchase applications were down 4% from the previous week and 14% from a year earlier.
Existing-home sales fell 2% in August to a seasonally adjusted annual rate of 3.98 million and were 1.2% below the previous year. Pending sales were also 4.7% lower than a year earlier.
Yet the median existing-home price was still 1.6% higher than a year earlier.
That is the affordability trap.
Higher mortgage rates are suppressing demand, but prices remain supported by limited supply, homeowner lock-in, regional shortages and the fact that many owners are under little pressure to sell.
Inventory has improved. NAR reported 1.62 million existing homes for sale in August, the highest level since 2019 and equivalent to 4.9 months of supply.
New-home builders are responding more aggressively.
Commerce Department data showed the median price of a newly sold home fell to $393,700 in August, down 5.8% from a year earlier, while builders have increasingly used price reductions and financing incentives to move inventory.
That may create opportunities for some buyers.
It does not erase the nationwide affordability gap.
The early 1980s were worse — but that does not make today affordable
Historical comparisons need an important qualification.
Mortgage rates reached 18.63% in 1981, according to Freddie Mac — far above anything Americans face today.
Buyers in that era endured genuinely extreme financing conditions, and it would be misleading to claim that a 7% mortgage in 2026 is inherently worse than an 18% mortgage in 1981.
The more relevant comparison is with previous periods when rates themselves were around 7%.
In 2001, 7% financing existed alongside a home-price structure that was far more favorable relative to income. Historical NAR data show housing affordability was substantially stronger then than it is now.
Today’s crisis therefore is not that 7% is an unprecedented interest rate.
It is that Americans are paying 7% on historically expensive homes.
That is a fundamentally different burden.
The people locked out lose more than a house
Homeownership in America has never been merely about shelter.
For generations, it has also functioned as a major household wealth-building mechanism. Mortgage payments gradually convert debt into equity. Rising property values can create wealth that later supports education, retirement, business formation or inheritance.
When families are delayed from buying, they potentially miss years of that equity accumulation.
NAR estimates that delaying homeownership from around age 30 to around age 40 can translate into substantial lost housing equity over time, although the eventual outcome depends heavily on future home prices, location and how long a household owns the property.
The effect also reaches family life.
Only 24% of recent home buyers in NAR’s 2025 profile had children younger than 18, the lowest share in its data. Housing costs are not the sole explanation — Americans are having fewer children and buyers themselves are older — but NAR also cited child-care expenses and broader affordability pressures as factors limiting families’ ability to save.
The national homeownership rate stood at 65.0% in the second quarter of 2026, essentially unchanged from a year earlier.
That headline stability can conceal the distribution underneath.
Older owners may possess low-rate mortgages and accumulated equity.
Younger households may be paying high rents while trying to save an $80,000 down payment for a home financed near 7%.
The housing market can therefore look stable statistically while becoming progressively harder to enter.
What happens next
There is no guarantee that mortgage rates will fall quickly.
The Federal Reserve raised its federal funds target range by a quarter percentage point to 3.75% to 4% on September 16, citing inflation that remained above its 2% goal. Mortgage rates do not move mechanically with the federal funds rate — they are heavily influenced by longer-term Treasury yields, inflation expectations and mortgage-market spreads — but the broader interest-rate environment matters.
The Mortgage Bankers Association said after the Fed decision that it expected mortgage rates to remain near current levels over its forecast horizon. Forecasts are inherently uncertain and can change quickly with inflation, economic growth, bond markets and geopolitical conditions.
Freddie Mac’s next weekly mortgage-rate reading is scheduled for October 1 at noon Eastern time. September existing-home sales are due from NAR on October 13, while the Federal Reserve’s next policy meeting is scheduled for October 27–28.
Lower mortgage rates would help immediately.
But rates alone cannot restore the housing market Americans knew two decades ago.
A decline from 7% to 6% reduces the monthly payment on a large mortgage, but it does not erase a $400,000 purchase price, an $80,000 down payment requirement, rising insurance premiums or years of housing-price growth that outran incomes.
That is the deeper lesson behind today’s 7% mortgage.
The percentage is not historically shocking.
The principal beneath it is.
And for families trying to buy their first home, that multiplication of high prices, expensive debt and rising ownership costs can turn an ordinary interest rate into an extraordinary barrier to one of America’s traditional paths to financial security.
Sources
- Freddie Mac — Primary Mortgage Market Survey, Sept. 24, 2026
https://www.freddiemac.com/pmms - Mortgage Bankers Association — Mortgage Applications Decrease in Latest MBA Weekly Survey, Sept. 30, 2026
https://www.mba.org/news-and-research/newsroom/news/2026/09/30/mortgage-applications-decrease-in-latest-mba-weekly-survey - National Association of Realtors — Existing-Home Sales, August 2026
https://www.nar.realtor/newsroom/nar-existing-home-sales-report-shows-2-0-decrease-in-august - U.S. Census Bureau — Income in the United States: 2025
https://www.census.gov/library/publications/2026/demo/p60-289.html - U.S. Census Bureau — Money Income in the United States: 2001
https://www.census.gov/library/publications/2002/demo/p60-218.html - HUD User — Historical Housing Affordability Data, including 2001 prices and mortgage rates
https://www.huduser.gov/periodicals/ushmc/spring03/histdat11.htm - Harvard Joint Center for Housing Studies — State of the Nation’s Housing 2026
https://www.jchs.harvard.edu/state-nations-housing-2026 - Harvard Joint Center for Housing Studies — Ten Takeaways from the 2026 State of the Nation’s Housing
https://www.jchs.harvard.edu/blog/ten-takeaways-2026-state-nations-housing - Federal Housing Finance Agency — House Price Index, Sept. 29, 2026
https://www.fhfa.gov/news/news-release/fhfa-house-price-index-up-0.3-percent-in-july-up-2.6-percent-from-last-year - S&P Dow Jones Indices — Case-Shiller July 2026 Home Price Index
https://www.spglobal.com/spdji/en/index-announcements/article/sp-cotality-case-shiller-index-reports-annual-gain-in-july-2026/ - National Association of Realtors — 2025 Profile of Home Buyers and Sellers
https://www.nar.realtor/press-releases/first-time-home-buyer-share-falls-to-historic-low-of-21-median-age-rises-to-40 - Federal Reserve — July 2026 Monetary Policy Report, housing and mortgage lock-in
https://www.federalreserve.gov/monetarypolicy/2026-07-mpr-part1.htm - U.S. Census Bureau — Quarterly Residential Vacancies and Homeownership, Q2 2026
https://www.census.gov/housing/hvs/current/ - Federal Reserve — FOMC Statement, Sept. 16, 2026
https://www.federalreserve.gov/newsevents/pressreleases/monetary20260916a.htm - National Association of Realtors — Pending Home Sales, August 2026
https://www.nar.realtor/newsroom/nar-pending-home-sales-report-shows-0-point-3-percent-increase-in-august

Leave a Reply