Oct 1, 2026
A Provo startup called NestSTEPS is pitching Utah employers on a new kind of workplace perk: help buying a home. The company offers payroll-linked savings for a down payment, employer contributions modeled on a 401(k) match, and one-on-one homebuying coaching. Co-founder Cheri Salazar told KSL in early September that NestSTEPS was working with 11 Utah companies, and The Salt Lake Tribune profiled the program on September 26, 2026.
The timing is no accident. Utah’s median home sale price was about $520,000 in August, according to early Kem C. Gardner Policy Institute data cited by KSL, and Gov. Spencer Cox has acknowledged that state efforts to bring prices down are not working. Into that gap, private employers and the startups that serve them are offering what government has not.
For a young worker priced out of a first home, an employer match on a down payment can be real money. But tying the biggest purchase of a person’s life to a job raises old questions in new packaging. What happens to the money if you quit, who profits from the transaction, and how much of your financial life your employer gets to see are questions every worker should ask before signing up.
What the benefit actually is
Nothing in published accounts describes NestSTEPS as a mortgage lender, or employers in its program as holders of their workers’ home loans. According to KSL, the platform combines a savings tool for down payments, employer contribution plans similar to 401(k) matching, and education on budgeting and homebuying.
In an interview with TechBuzz News, co-founder and president Larry Salazar described how the software works. Paychecks are routed first into a dedicated savings account rather than a checking account. If a worker tries to withdraw money for something other than housing, the app shows how much the withdrawal would delay their purchase, such as a warning of a three-month setback. Workers also get guidance from staff the company calls “Home Advisors” and “Equity Architects.”
Employers choose how much to contribute. TechBuzz reported that contributions typically range from $3,000 to $10,000 as flat down payment help, and some employers instead fund ongoing principal paydowns for workers who already own homes.
NestSTEPS earns money from platform fees and from referral fees paid by real estate agents who help participating workers buy, Cheri Salazar told KSL. One early user, 24-year-old Jared Bowen, told KSL the coaching gave him the confidence that buying was “an attainable goal.” He was closing on his first house in Saratoga Springs in early September.
Why Utah, and why now
Utah lawmakers have passed bills and launched initiatives aimed at housing affordability, but KSL reports that Gov. Spencer Cox recently acknowledged those efforts are not working. KSL notes the market remains especially hard for first-time buyers.
NestSTEPS says it first targeted construction, education and health systems, then found unexpected demand among tech companies and mid-sized firms, according to TechBuzz. That puts the product squarely in Silicon Slopes, the tech corridor stretching from Salt Lake County into Utah County, where employers compete hard for young talent.
The company is now scaling through professional employer organizations (PEOs) and benefits brokers, which bundle HR services for many small businesses at once. TechBuzz reported that these partnerships are expected to bring the platform to several hundred businesses across the Intermountain West in early 2027. Cheri Salazar told KSL that one recent company meeting produced 58 sign-ups on the spot.
Utah is part of a national trend. Fortune reported in April that employers are adding home-buying help as a recruiting and return-to-office tool, citing grants of up to $10,000 at Fannie Mae and $15,000 at Freddie Mac for eligible workers. Rival startups such as Foyer, which markets itself as a “401(k) for homeownership,” are chasing the same employers.
The company-town echo
America has tried tying housing to employers before. In the 1880s, the Pullman Company built a model town outside Chicago and owned every building in it, charging rents meant to earn a return on its investment, according to the 2015 presidential proclamation creating the Pullman National Monument. When the company cut wages in a downturn but did not cut rents, workers walked out in May 1894, sparking one of the largest labor actions in U.S. history.
Today’s programs are very different. Workers own their homes, and the employer’s role is limited to a contribution and a software subscription. No one is proposing that a boss collect rent or run the town.
In our reading, the lasting lesson of Pullman is about leverage, not architecture. When the same institution controls your paycheck and a key part of your housing, your bargaining power shrinks. The modern question is whether home benefits are designed to free workers or to bind them, and the answer depends on fine print that is often not public.
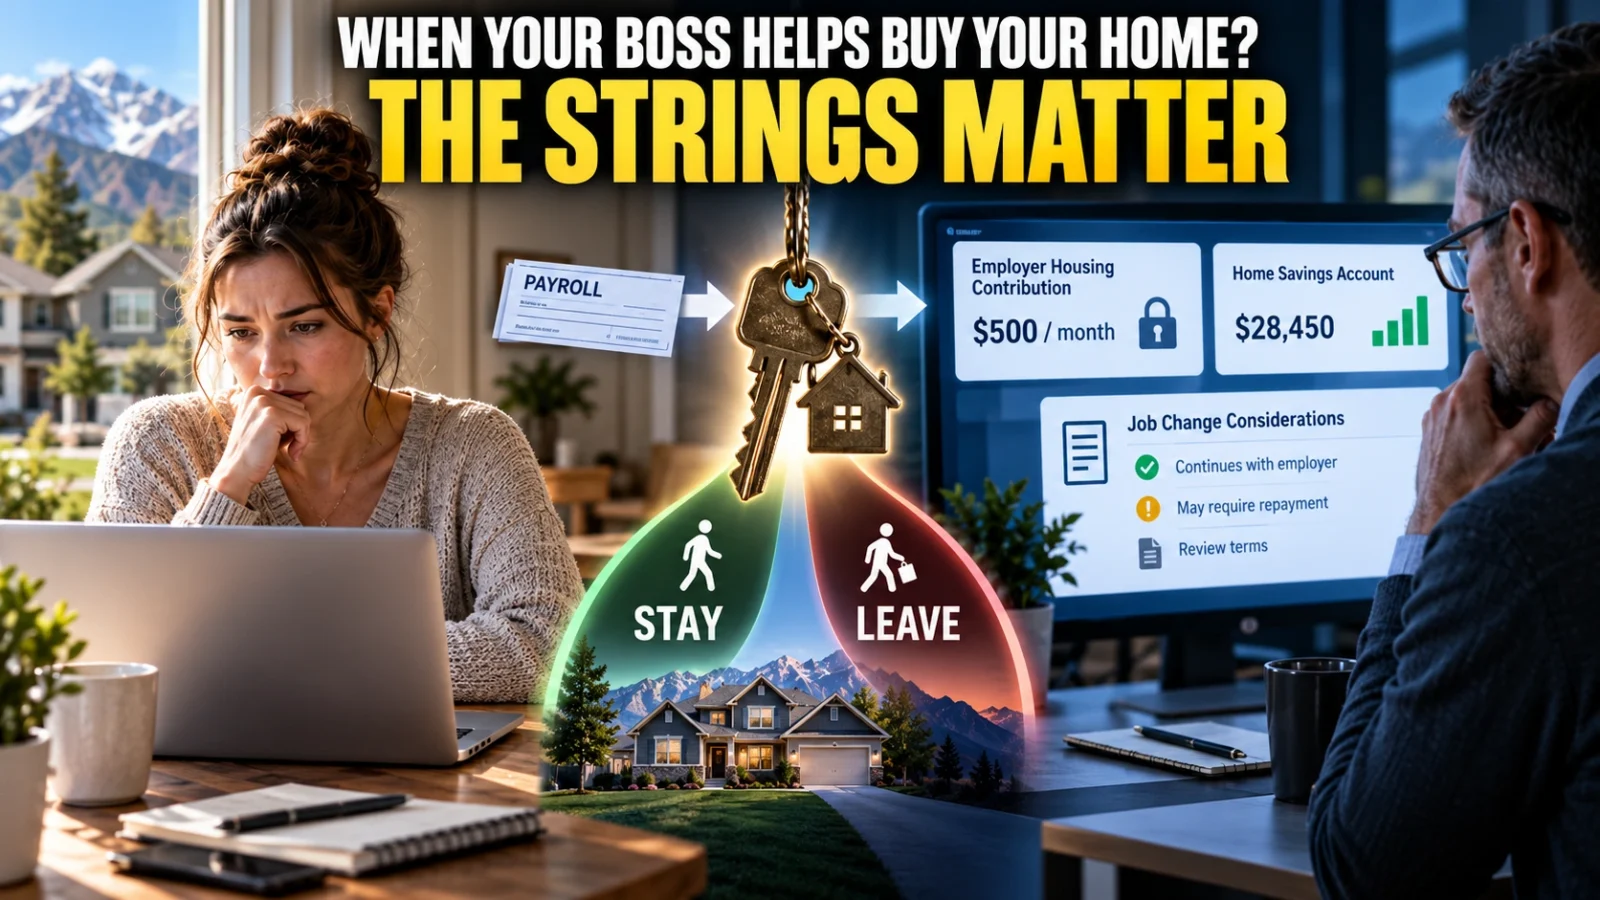
The strings: what happens if you quit?
NestSTEPS openly sells retention. Larry Salazar told TechBuzz that workers in housing assistance programs are 50% to 65% less likely to leave than non-participants, a figure the company attributes to historical data and which The Voice of Human could not independently verify. A benefit built to reduce turnover works partly by making it costlier to leave.
The clearest public model shows how that can happen. Colorado created a tax credit in 2023 for employers that fund employee home savings accounts. Under that law, a worker who leaves the job forfeits any unspent employer contributions, according to an April 2026 review by Colorado’s Office of the State Auditor. The worker keeps only their own deposits plus interest.
NestSTEPS’ published materials reviewed for this article do not spell out what happens to employer money when a participant changes jobs. That is a question for each employer, and workers should get the answer in writing before enrolling.
Federal regulators have warned about similar “stay or pay” arrangements in other contexts. A 2023 report by the Consumer Financial Protection Bureau found that debts tied to employment can limit workers’ ability to switch jobs for better pay, partly because the employer controls both the debt and the paycheck. A forfeitable housing match is not a debt, but it can create a similar pull to stay.
| Program | Employer help | Notable terms |
|---|---|---|
| NestSTEPS (Utah) | Typically $3,000–$10,000, set by employer | Paycheck routed to dedicated savings; departure rules not published |
| Colorado employer credit (2024–2026) | Employer gets credit of 5% of contribution, up to $5,000 per worker | Worker forfeits unspent employer money on leaving |
| BNY (April 2026) | $6,500 for workers earning $100,000 or less | First home only; subject to income taxes |
| Fannie Mae | Up to $10,000 one-time grant | For eligible employees, per Fortune |
| Freddie Mac | $15,000 subsidy | Eligible first-time buyers, per Fortune |

Leave a Reply