Oct 8, 2026 · @Som Bentur
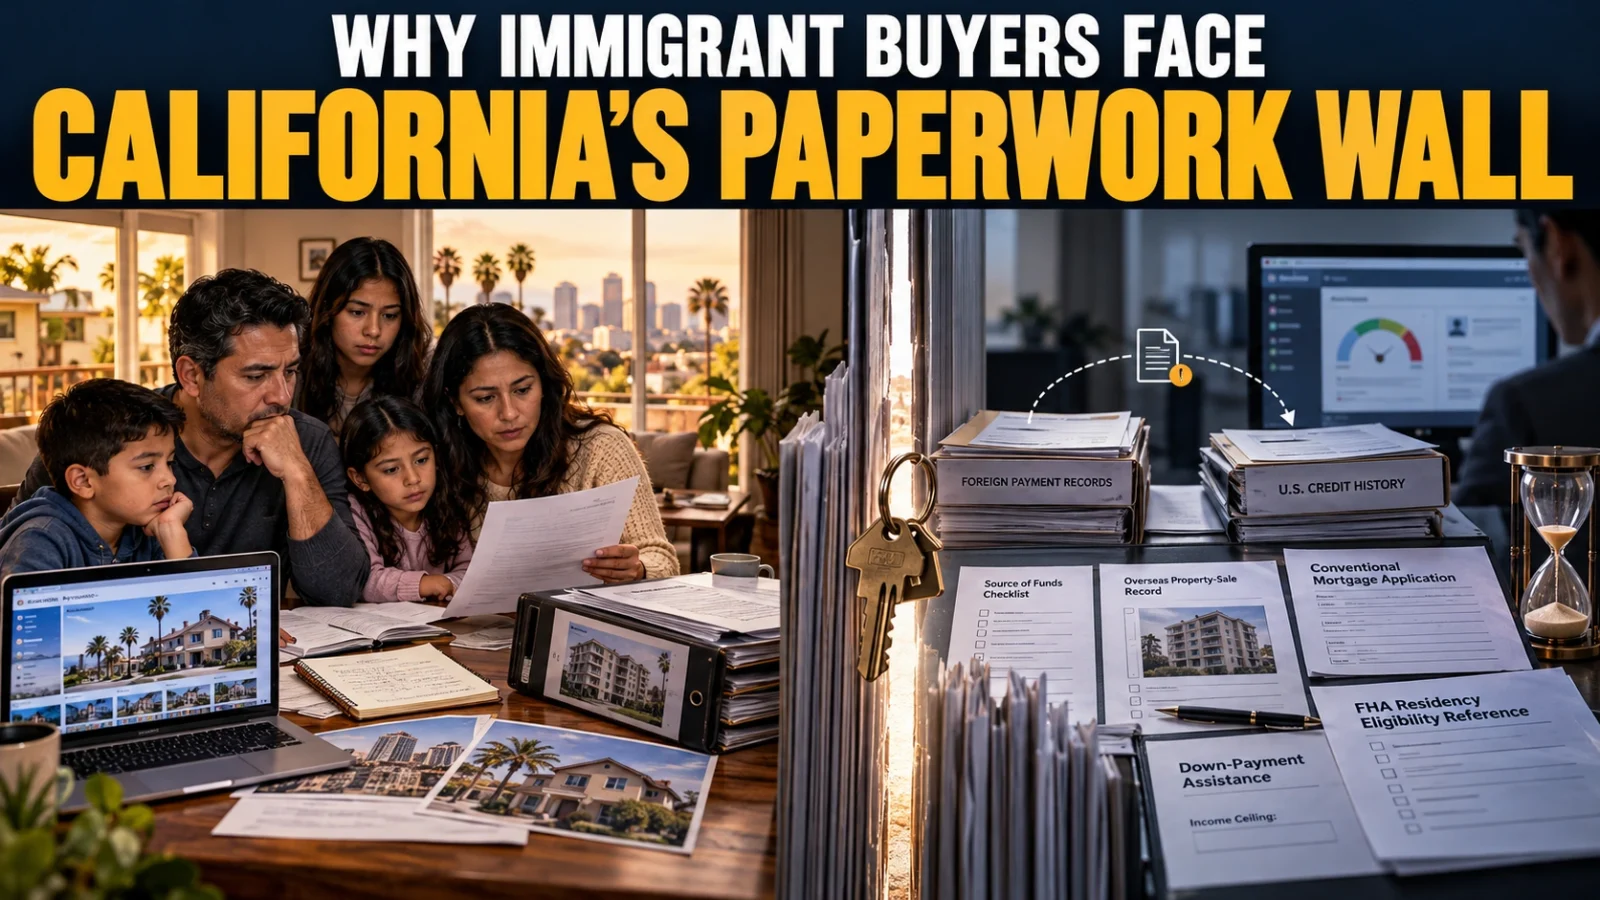
A family of five in San Diego has steady income, savings and a history of owning property. They cannot buy a home. That is the case Anastasiia Chystiukhina, a San Diego realtor who emigrated from Ukraine in 2022, laid out in a published September 29, 2026. The family’s down payment is tied up in an overseas apartment whose sale proceeds can only reach them as cash, which no lender can accept without a paper trail. Their fifteen years of on-time mortgage and utility payments abroad do not appear on any U.S. credit report. They earn slightly too much for assistance programs and are too new for the market.
The argument lands at a specific moment. In 2025 the Federal Housing Administration ended mortgage eligibility for non-permanent residents, including DACA recipients and work-visa holders, and federal regulators this year loosened the credit-scoring rules the op-ed hopes will eventually help. California’s legal net immigration fell by nearly half between 2024 and 2025, from 248,000 to 126,000, and the state’s population declined for the first time in years. Home prices did not fall with it.
Who is affected: the roughly 28 percent of Californians born abroad, most of them of working age, and in particular the ones who have done everything the system asks except arrive early enough to build a paper trail. Chystiukhina’s question is the one this article tries to answer: who is being locked out not by price, but by paperwork?
Three walls, none of them a price tag
The first wall is the money itself. A buyer who sells a house in Ohio gets a wire from escrow, and the paperwork, as Chystiukhina puts it, writes itself. A buyer whose apartment in a war zone or a capital-controlled economy can only be liquidated for cash runs into anti-money-laundering rules that require every large deposit to be sourced. The rule is the same for everyone; its weight is not. The down payment exists, the lender cannot count it, and the house the family can qualify for “drops a tier.”
The second wall is credit. Fifteen years of on-time mortgage and utility payments in Kyiv, Guadalajara or Manila do not transfer to Equifax, Experian or TransUnion. A newcomer starts at zero, and a conventional mortgage underwritten on Classic FICO, the model Fannie Mae and Freddie Mac required for decades, reads zero as risk. Chystiukhina arrived in 2022 having run a business for years and found none of it on her U.S. report.
The third wall is the gap between programs. San Diego’s Housing Commission offers deferred loans and closing-cost grants, and the California Housing Finance Agency has its own products; she says she has used them with clients and they work. But they carry income ceilings. A family that earns slightly too much is, in her words, “too well-off for help and too new for the market,” left with the bottom of the inventory not because they cannot afford the middle but because the middle demands a credit file that takes years to build.
Washington closed one door and cracked another
The op-ed does not mention it, but the largest recent change for immigrant buyers came from the federal government. On March 26, 2025, HUD issued , which ended FHA mortgage eligibility for all non-permanent residents effective May 25, 2025. FHA loans, with their 3.5 percent down payments and 580 minimum credit scores, had been the entry point for buyers with thin files. The new rule excludes DACA recipients, H-1B and other work-visa holders, asylum seekers without green cards and, by lender guidance, mixed-status households where one borrower lacks permanent residency. HUD described the change as aligning FHA with federal priorities favoring citizens and permanent residents; it has not published how many borrowers the old policy served.
At the same time, the credit-scoring door has opened, slowly. In July 2025 the Federal Housing Finance Agency allowed lenders to use VantageScore 4.0 instead of Classic FICO; a limited rollout began , and on September 3 FHFA Director Bill Pulte ordered Fannie Mae and Freddie Mac to accept the model from every approved lender. VantageScore 4.0 and FICO 10T can incorporate rent, utility and phone payments. That is the “federal mortgage standards shifted this year” the op-ed refers to.
Two caveats shrink the benefit. Those models count rent and utility payments only if a landlord or consumer has opted to report them to the bureaus, which most do not, CNBC reported. And none of it helps a buyer whose payment history is in another country. As Chystiukhina writes, a rule change in Washington and a loan officer applying it in San Diego “are two different events, likely years apart.”
The numbers behind the gap
| Measure | Figure | Source |
|---|---|---|
| Californians born outside the U.S. | About 28% | CalMatters commentary |
| Statewide median single-family price, August 2026 | $901,420 | California Association of Realtors |
| Households able to afford a median-priced home, 2025 | 19% statewide; 11% of Hispanic/Latino households | C.A.R. affordability index |
| Minimum income for a median-priced home, Q1 2026 | $204,800 | C.A.R. |
| San Diego County households able to afford the median home | About 17% | Commentary, citing C.A.R. |
| California homeownership rate, 2024 | 55.8% overall; 45.9% Hispanic/Latino | Census ACS via C.A.R. |
| California legal net immigration, 2024 to 2025 | 248,000 to 126,000 | CalMatters |
| FHA eligibility ended for non-permanent residents | May 25, 2025 | HUD Mortgagee Letter 2025-09 |
| VantageScore 4.0 opened to all Fannie/Freddie lenders | September 3, 2026 | FHFA |
The affordability figures describe income, not paperwork. A family above the $204,800 threshold is, by C.A.R.’s math, one of the one in five that can afford the median home. That is the family Chystiukhina describes: qualified on income, blocked on documentation. The association itself attributes the ethnic gap in part to “persistent barriers to credit access,” which is the same barrier in a different frame.
What a locked door costs a family
The arithmetic of renting instead of owning in California is unforgiving. C.A.R. puts the monthly payment on a median-priced home, with taxes and insurance, at about $5,120; a family paying comparable rent builds no equity, and in a state where the median home has roughly doubled in a decade, equity is the main way working households accumulate wealth. A family kept out for five years while it builds a credit file is not just delayed; it buys later, at a higher price, with a shorter horizon to pay the loan down.
The op-ed’s family is not undocumented and is not poor. That is the point. The cash they cannot deposit and the credit they cannot import are the kind of problems that policy debates about affordability, which focus on prices, rates and income, never reach. They end up, Chystiukhina writes, shopping “the bottom of the inventory” in a market where the bottom in San Diego is still well above the national median.
There is a second-order cost. California’s legal net immigration fell by nearly half between 2024 and 2025, and the state’s population fell for the first time in years, CalMatters has reported. Immigrants who cannot put down roots are more likely to leave, taking their income and their children with them. Chystiukhina frames it as a question the state has not asked itself: who is being quietly pushed out, not by price but by paperwork?
Is this redlining? What the law says, and what changed this year
Redlining, the term the brief invokes, describes lenders refusing credit to whole neighborhoods on the basis of race. The barriers in the op-ed are different in kind: they are facially neutral documentation rules that fall harder on newcomers. Nothing in the commentary alleges that any lender broke the law, and this article makes no such allegation. But the legal protections that would have caught discriminatory outcomes have been narrowed in 2026, which is why advocates are reaching for the word.
The Equal Credit Opportunity Act bars discrimination based on national origin. It has always allowed lenders to consider immigration status when it bears on ability to repay. What shifted is the balance. On January 12, 2026, the CFPB and Justice Department a 2023 joint statement warning lenders that blanket immigration-status rules could violate ECOA. In April, the CFPB finalized a rule declaring that ECOA does not support “disparate impact” claims, so a lending practice that excludes immigrants disproportionately is unlawful only if intent can be proven. In June, the bureau told lenders that immigration status in ability-to-repay analysis and flagged ITIN use as a possible indicator of removal risk, while reminding them that national-origin discrimination remains illegal.
Lawyers on both sides call that a catch-22. Ballard Spahr’s Rich Andreano said the guidance raises the risk of ignoring immigration status without saying how to consider it lawfully. The National Consumer Law Center argues that treating all ITIN holders as deportation risks is “discriminatory and unreasonable,” and notes that California, New York and Washington bar discrimination based on citizenship or immigration status under state law. Whether a lender’s conservative response to federal guidance crosses a state line is a question no court has yet answered.
What California has tried, and what buyers can do now
The state’s main answer has been down-payment help, and it has been both oversubscribed and politically contested. The California Dream for All program, which offers first-time buyers up to 20 percent of a purchase price as a shared-appreciation loan, ran out of money within days of its 2023 launch. In 2024 the Legislature passed AB 1840 to bar the program from disqualifying applicants solely for immigration status; Gov. Gavin Newsom , citing the program’s limited funding rather than its eligibility rules. The program’s income ceilings are the gap the op-ed describes for families earning slightly too much.
Outside the government programs, the market has partial workarounds. Some community banks, credit unions and nonprofit lenders offer ITIN mortgages and portfolio loans that accept foreign credit reports or 12 months of documented rent and utility payments in place of a FICO score; these loans are not sold to Fannie Mae or Freddie Mac and typically carry higher rates and larger down payments. The CFPB’s June guidance, which flagged ITIN use as a possible indicator of removal risk, has made some of those lenders more cautious, Ballard Spahr noted.
Chystiukhina’s own prescription is not another program. It is information delivered earlier: before a family begins looking, not mid-transaction when they discover their cash cannot be sourced or their credit does not exist. Practically, that means opening U.S. accounts and a secured credit card on arrival, moving down-payment funds through traceable channels well before an offer, opting in to rent reporting with a landlord, and asking a lender up front whether it uses VantageScore 4.0 or accepts foreign credit histories.
What happens next
The credit-scoring change is the one moving piece. With VantageScore 4.0 now open to every Fannie and Freddie lender and FICO 10T scheduled to follow, the question for 2027 is whether loan officers in San Diego actually use the new models and whether landlords report rent. FHFA has said the historical score data is now public for lenders to test. The FHA residency rule shows no sign of reversal, and HUD’s own cost-benefit analysis of it has not been published.
On fair lending, the CFPB has said more guidance on immigration status will follow. State regulators in California, which bars discrimination based on immigration status, have not said how they will treat lenders that tighten standards in response to federal signals. For the family in the op-ed, none of this is fast. Their realistic path is the one Chystiukhina lays out: build the paper trail now, and buy when the system can finally read it.
Editorial note: The San Diego family is described in a guest commentary by a realtor who represents them; their details have not been independently verified. The commentary makes no allegation of unlawful conduct by any lender, and none is made here. The “redlining” framing in the brief is used as an analogy to facially neutral rules with disparate effects, not as a legal characterization. Statements about ITIN lenders’ caution and the compliance “catch-22” are attributed to law-firm and advocacy commentary.
Sources
CalMatters, Anastasiia Chystiukhina, “How immigrants get locked out of buying a California home — even when they can afford it,” September 29, 2026 — https://calmatters.org/commentary/2026/09/immigrant-homebuyers-locked-out-california/
Times of San Diego, earlier version of the commentary, September 11, 2026 — https://timesofsandiego.com/opinion/2026/09/11/how-the-system-works-against-immigrant-home-buyers/
NCSHA, FHA Mortgagee Letter 2025-09: Revisions to Residency Requirements — https://www.ncsha.org/resource/fha-mortgagee-letter-2025-09-revisions-to-residency-requirements/
National Mortgage Professional, “No FHA-Insured Loans For Non-Permanent U.S. Residents” — https://nationalmortgageprofessional.com/news/no-fha-insured-loans-non-permanent-us-residents
FHFA, Credit Scores policy page — https://www.fhfa.gov/policy/credit-scores
Congressional Research Service, “Fannie Mae and Freddie Mac Adopt Alternative Credit Scores” (IF12588) — https://www.congress.gov/crs-product/IF12588
Scotsman Guide, “Pulte instructs Fannie Mae and Freddie Mac to accept VantageScore for all lenders” — https://www.scotsmanguide.com/news/pulte-instructs-fannie-mae-and-freddie-mac-to-accept-vantagescore-for-all-lenders/
CNBC, “Mortgage lenders now have more credit score options” — https://www.cnbc.com/2026/05/05/mortgage-lenders-now-have-more-credit-score-options-what-to-know.html
California Association of Realtors, 2025 Housing Affordability by Ethnicity — https://www.car.org/aboutus/mediacenter/newsreleases/2026releases/HAI2025byEthnicity
California Association of Realtors, First Quarter 2026 Housing Affordability — https://www.car.org/aboutus/mediacenter/newsreleases/2026releases/1qtr2026hai
HousingWire, “CFPB guidance points mortgage lenders to consider borrower immigration status” — https://www.housingwire.com/articles/cfpb-immigration-status-guidance/
National Mortgage Professional, “CFPB Tells Lenders Immigration Status Can Factor Into ATR Analysis” — https://nationalmortgageprofessional.com/news/cfpb-tells-lenders-immigration-status-can-factor-atr-analysis
Cooley, fair lending regulatory updates (withdrawal of 2023 joint statement; FHFA repeal) — https://finsights.cooley.com/tag/fair-lending/
American Banker, “CFPB finalizes new ECOA rule in major fair lending pivot” — https://www.americanbanker.com/news/cfpb-finalizes-new-ecoa-rule-in-major-fair-lending-pivot
Ballard Spahr, Mortgage Banking Update, August 27, 2026 — https://www.ballardspahr.com/insights/alerts-and-articles/2026/08/27-mortgage-banking-update
National Consumer Law Center, “Federal Attack on Immigrant Banking and Credit” — https://library.nclc.org/article/federal-attack-immigrant-banking-and-credit
CapRadio (AP), “California governor vetoes bill to make immigrants without legal status eligible for home loans” — https://www.capradio.org/articles/2024/09/06/california-governor-vetoes-bill-to-make-immigrants-without-legal-status-eligible-for-home-loans/
California Senate Housing Committee analysis, AB 1840 — https://shou.senate.ca.gov/system/files/2024-06/3-ab-1840-arambula-analysis.pdf

Leave a Reply